About
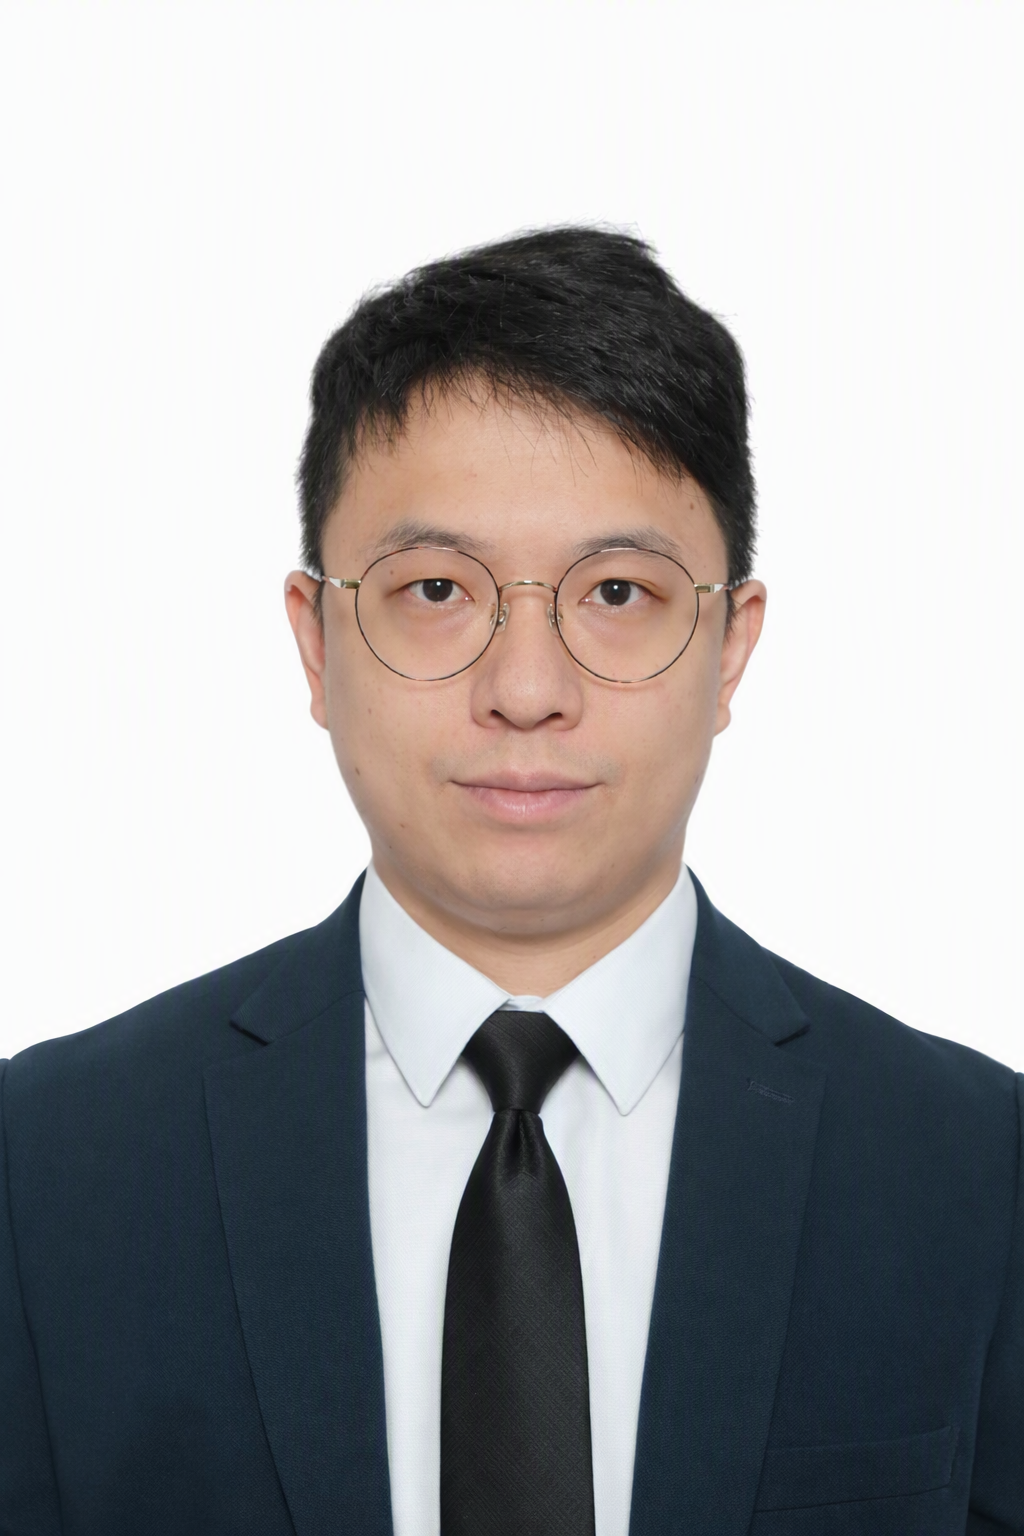
Lupe Shun Hin Chan is a Postdoctoral Fellow in the Department of Social Sciences and Policy Studies at The Education University of Hong Kong. Building on his Ph.D. and MPhil theses, he advances innovative methodologies for analyzing high‑dimensional, multimodal data. His work integrates artificial intelligence techniques with Bayesian inference to reveal complex dependence structures and causal relationships across diverse domains.
Dr. Chan’s research expertise encompasses Bayesian networks, network analysis, machine learning, and large language models (LLMs). In healthcare analytics, his projects include depression detection, automated psychosocial chatbots, and triage systems for severe psychosocial cases, demonstrating how statistical rigor can enhance early intervention and patient support. In financial risk modeling, he has developed the Graphical GARCH model and dynamic network models for portfolio optimization, offering scalable solutions for capturing nonlinear dependencies and systemic risk.
Through this interdisciplinary portfolio, Dr. Chan bridges methodological innovation with practical impact, contributing to both the advancement of statistical science and its application in pressing societal and economic challenges.
- PhD (Operations Management, Statistics Stream), The Hong Kong University of Science and Technology (HKUST) (2021–2024)
- MPhil (Operations Management, Statistics Stream), HKUST (2019–2021)
- Master of Statistics, The University of Hong Kong (2016–2017)
- BSc in Mathematics, HKUST (2012–2015)
-
Silver Medal, Silicon Valley International Invention Festival (SVIIF 2026)
Project: ASAP: Automatic Speech Analytics Program for Early Personalised Psychosocial Health Assessment
Team: Chu, AMY, So, MKP, Chan, LSH -
Silver Medal, International Invention Innovation Competition in Canada (iCAN 2026)
Project: ASAP: Automatic Speech Analytics Program for Early Personalised Psychosocial Health Assessment
Team: Chu, AMY, So, MKP, Chan, LSH -
Bronze Medal, International Exhibition of Inventions Geneva (2026)
Project: ASAP: Automatic Speech Analytics Program for Early Personalised Psychosocial Health Assessment
Team: Chu, AMY, So, MKP, Chan, LSH, CHAN, JNL -
Outstanding Innovation and Creativity Award, AI in Education Competition (2026)
Project: Enhancing Academic Performance Through AI‑Assisted Pedagogy
Team: So, MKP, Chu AMY, Tiwari A, Chan, LSH, Chan, JNL -
Outstanding Student Poster Award, EAC‑ISBA Conference (2024)
Poster Entitled: Dynamic Bayesian Networks with Conditional Dynamics in Edge Addition and Deletion
Chan, LSH
- Bayesian Networks
- Dynamic Modeling of Finance
- Healthcare Analytics
- Machine Learning
Thesis
This dissertation develops scalable Bayesian dynamic network methodologies for analyzing complex, multimodal datasets in healthcare and finance.
Introduces a hybrid MCMC approach for structural learning in Bayesian networks, improving efficiency in high-dimensional applications.
Teaching
BUS6032 Quantitative Analysis for Financial Studies (Fall 2025)
ISOM2500 Business Statistics (Summer 2022)
ISOM2600 Introduction to Business Analytics (Fall 2021)
ISOM3540 Introduction to Probability Models (Fall 2023)
ISOM4520 Statistics for Financial Risk Management (Spring 2020, Spring 2023)
ISOM5620 Visual Analytics for Business Decisions (Fall 2021)
ISOM2500 Business Statistics (Fall 2018, Spring 2019)
ISOM3530 Business Data Analysis (Spring 2019)
ISOM5535 High-Dimensional Statistics (Spring 2019)
Featured Papers
Using Valence and Arousal Scoring in Speech to Detect Depressive Symptoms: A Study on Family Caregivers (2026)
Authors: So, MKP, Tsang, JTY, Chan, LSH, Chan, JNL, Tiwari, A, and Chu, AMY
PLOS One
This study investigates the use of sentiment analysis in speech to improve early detection of depressive symptoms among family caregivers. By analyzing verbal responses from 116 participants with the Chinese Valence-Arousal Words dictionary, researchers computed statistical and frequency-based features of emotional word distributions and applied them to nine machine learning models under rigorous nested cross-validation. Results showed that individuals with higher depressive symptoms tended to use words with more extreme valence and arousal scores, and the quadratic discriminant analysis model performed well (sensitivity = 0.725, specificity = 0.563, AUC = 0.7). The high sensitivity highlights the method’s ability to reliably identify individuals with elevated symptoms, reducing missed cases while maintaining clinically relevant specificity. These findings provide proof-of-concept evidence that valence and arousal scoring can capture linguistic markers of depression, laying the groundwork for non-intrusive, automated mental health screening tools.
Forthcoming.Graphical Copula GARCH Modeling with Dynamic Conditional Dependence (2026)
Authors: Chan, LSH, Chu, AMY, and So, MKP
Journal of Business & Economic Statistics
Modeling returns on large portfolios is a challenging problem since the number of parameters in the covariance matrix grows quadratically as the size of the portfolio increases. In this article, we aim to develop a framework to model the nonlinear dependencies dynamically, namely the graphical copula GARCH (GC-GARCH) model. Motivated by the capital asset pricing model, one component of our model is independence among stock returns given some risk factors; this can greatly reduce the number of parameters, allowing the modeling of large portfolios. The joint distribution of the risk factors is factorized using a directed acyclic graph (DAG) with a pair-copula construction (PCC) to enhance the modeling of the tails of the return distribution while capturing complex dependent structures. The DAG induces topological orders to the risk factors which can be regarded as a list of directions of the flow of information. Dynamic conditional dependence structures are incorporated to allow the parameters in the copulas to be time varying. A three-stage estimation is used to estimate parameters in the marginal distributions, the risk factor copulas, and the stock copulas. The simulation study shows that the proposed estimation procedure effectively estimates the parameters and the underlying DAG structure with high accuracy. In the investment experiment presented in the empirical study, we show that the GC-GARCH model produces portfolios that, on average, yield higher returns, lower standard deviations, reduced turnover rates—indicating lower transaction costs—and greater diversification when compared to two competing copula-based models in the literature.
Read PublicationA Hybrid Markov Chain Monte Carlo Approach for Structural Learning in Bayesian Networks Based on Variable Blocking (2025)
Authors: Chan, LSH, Chu, AMY, and So, MKP
Bayesian Analysis
Bayesian networks are models to represent dependence structures among variables through a directed acyclic graph (DAG). Structural learning refers to the statistical estimation of the DAG configuration. A challenge in structural learning is that the number of possible DAG grows super-exponentially as the number of variables increases. Most existing works discover structures over either the DAG space or the topological order space. We propose a hybrid approach that uses Markov chain Monte Carlo (MCMC) to learn Bayesian networks from data, making use of both the DAG space and the topological order space. A key feature of the proposed method is to partition the variables of similar topological orders into blocks. We introduce a hybrid MCMC approach where the structure search is conducted over the DAG space within each block to promote more targeted edge moves, and the across-block search is done to ensure the ergodicity of the Markov chain. A main innovation in our hybrid MCMC with blocking is to make use of the topological order in Bayesian networks to mimic natural time sequence in time series. Both simulation and empirical results suggest that the propose blocking idea with the hybrid MCMC enhances the efficiency in structural learning.
Read PublicationUtilizing Google Trends Data to Enhance Forecasts and Monitor Long COVID Prevalence (2025)
Authors: Chu, AMY, Tsang, JTY, Chan, SSC, Chan, LSH, and So, MKP
Communications Medicine
Long COVID is a persistent illness that follows COVID-19 infection. It has emerged as a significant public health concern since the outbreak of the pandemic. Effective disease surveillance is crucial for policy making and resource allocation. We investigate the potential of using the number of searches of long COVID symptoms in Google to enhance surveillance and improve the predictability of long COVID prevalence. We found searches for several specific symptoms increased both before and after searches for long COVID, demonstrating that numbers of searches can predict long COVID prevalence. Google search results could therefore be used to monitor disease prevalence.
Read PublicationInvited Conference Presentations
EcoSta 2026 – Ryukoku University, Kyoto
Topic: Integrating LLM sentiment, emotional word scoring, and syntactic dependency in speech for depression detection.
EcoSta 2025 – Waseda University, Tokyo
Topic: Utilizing Google Trends data to enhance forecasts and monitor long COVID prevalence.
EcoSta 2024 – Beijing Normal University, Beijing
Topic: Multi‑view dynamic social network modeling.
EAC‑ISBA Conference 2024 – The Education University of Hong Kong, Hong Kong
Topic: Dynamic Bayesian networks with conditional dynamics in edge addition and deletion.
EcoSta 2023 – Waseda University, Tokyo
Topic: Graphical copula GARCH modeling with dynamic conditional dependence.
Symposium on Applied Mathematics and Data Science 2023 – EdUHK, Hong Kong
Topic: A hybrid Markov chain Monte Carlo algorithm for structural learning in Bayesian networks.
IASC‑ARS Interim Conference 2022 – EdUHK, Hong Kong
Topic: A moving‑window Bayesian network model for assessing systemic risk in financial markets.
DSSV 2022 – National Cheng Kung University, Taiwan
Topic: Dynamic Bayesian network analysis for financial risk assessment.
EcoSta 2021 – HKUST, Hong Kong
Topic: Structural learning in Bayesian networks and its business applications.